Immersed is HOLDING nearly $2 MILLION in REFUNDABLE Visor pre-order deposits — and its latest SEC filing says there is SUBSTANTIAL DOUBT about the company’s ability to continue as a going concern. According to Mixed-News reporting on October 1, 2026, those figures come from Immersed’s Form 1-SA filed September 29 covering the six months ended June 30, 2026.
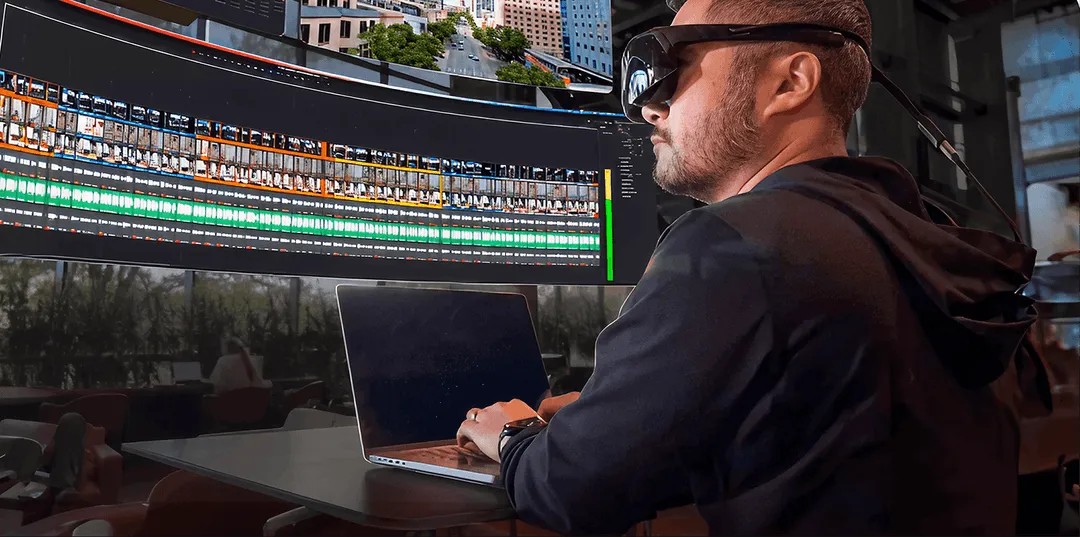
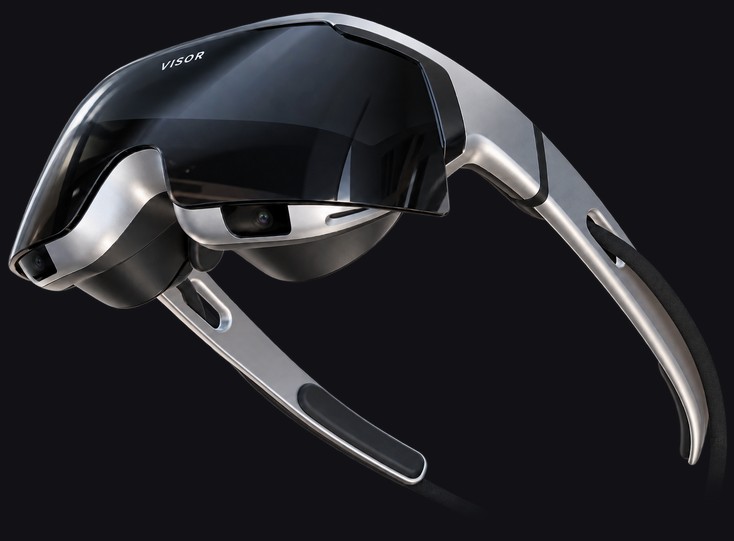
This is a FILINGS story, not a KEYNOTE. Immersed built its name on the Immersed virtual workspace app used across Quest, Vision Pro, and other headsets. Visor is the company’s OWN work-focused hardware play — marketed as a lighter, cheaper 4K-per-eye alternative for all-day productivity. Pre-orders date back to September 2023, so EARLY buyers have now WAITED THREE YEARS for volume shipping.
What the 1-SA Actually Shows
Mixed-News walks through the unaudited numbers Immersed reported for the half year. Net LOSS hit $12,576,581, versus $1,876,218 in the same period of 2025. Revenue was only about $0.16 MILLION, down from $0.49 million a year earlier. Cash and cash equivalents CLOSED at $3,757,201, against a WORKING capital deficit of $6,207,828 and an accumulated deficit of $48,107,993.
Operating expenses JUMPED to about $12.54 MILLION. Immersed attributes most of the rise to internet advertising of $5.09 million tied to its Regulation A+ share offering, stock-based compensation of $5.06 million, and professional fees of $0.82 million. Product DEVELOPMENT and contractor costs actually FELL. In other words, the LARGEST cost line was SELLING shares in Immersed itself — more than THIRTY TIMES the half-year revenue, on the company’s own accounting as summarized by Mixed-News.
Deposits Down, Production Still Targeted for Q4
Deferred revenue for Visor and Visor Plus deposits stood at $1,999,429 on June 30, 2026, down $216,868 from $2,216,297 at year-end 2025. The filing notes additional deposits arrived during the period but does NOT publish a refund TOTAL. Deposits stay as deferred revenue until units SHIP.
On HARDWARE timing, Immersed says evaluation units went out in 2025 and that LARGER batches of production units are TARGETED for Q4 2026 — subject to finishing development and manufacturing on schedule. Management’s mitigation plan, as quoted in the reporting, includes raising MORE capital through a private raise and public crowdfunding, hiring sales staff, and “aggressively selling” current and future products. Stock subscriptions received in advance of about $1.0 MILLION sat on the June 30 balance sheet.
Caveats That Matter for Readers
Two CAVEATS deserve EMPHASIS. First, Form 1-SA financials are UNAUDITED. Second, Immersed’s marketing claim that Visor is “70% lighter” and “70% less expensive” than other 4K-per-eye headsets appears in company materials WITHOUT a named comparison device, and the 1-SA itself gives NO Visor PRICE and NO unit COUNT. Public summaries also note Immersed expects subscription REVENUE to decline until Visor manufacturing and fulfillment RAMP, citing attrition on bulkier third-party headsets.
For the XR productivity niche, the filing is a CLEAR reality check. Software ADOPTION and STAGE demos are not the same as FULFILLED hardware. Immersed still POINTS to Q4 2026 for larger Visor production, while its own going-concern language puts capital RAISE and sales EXECUTION at the center of the next few quarters. Primary coverage: Mixed-News (Oct 1, 2026); Immersed’s investor materials remain at invest.immersed.com and product pages at visor.com.