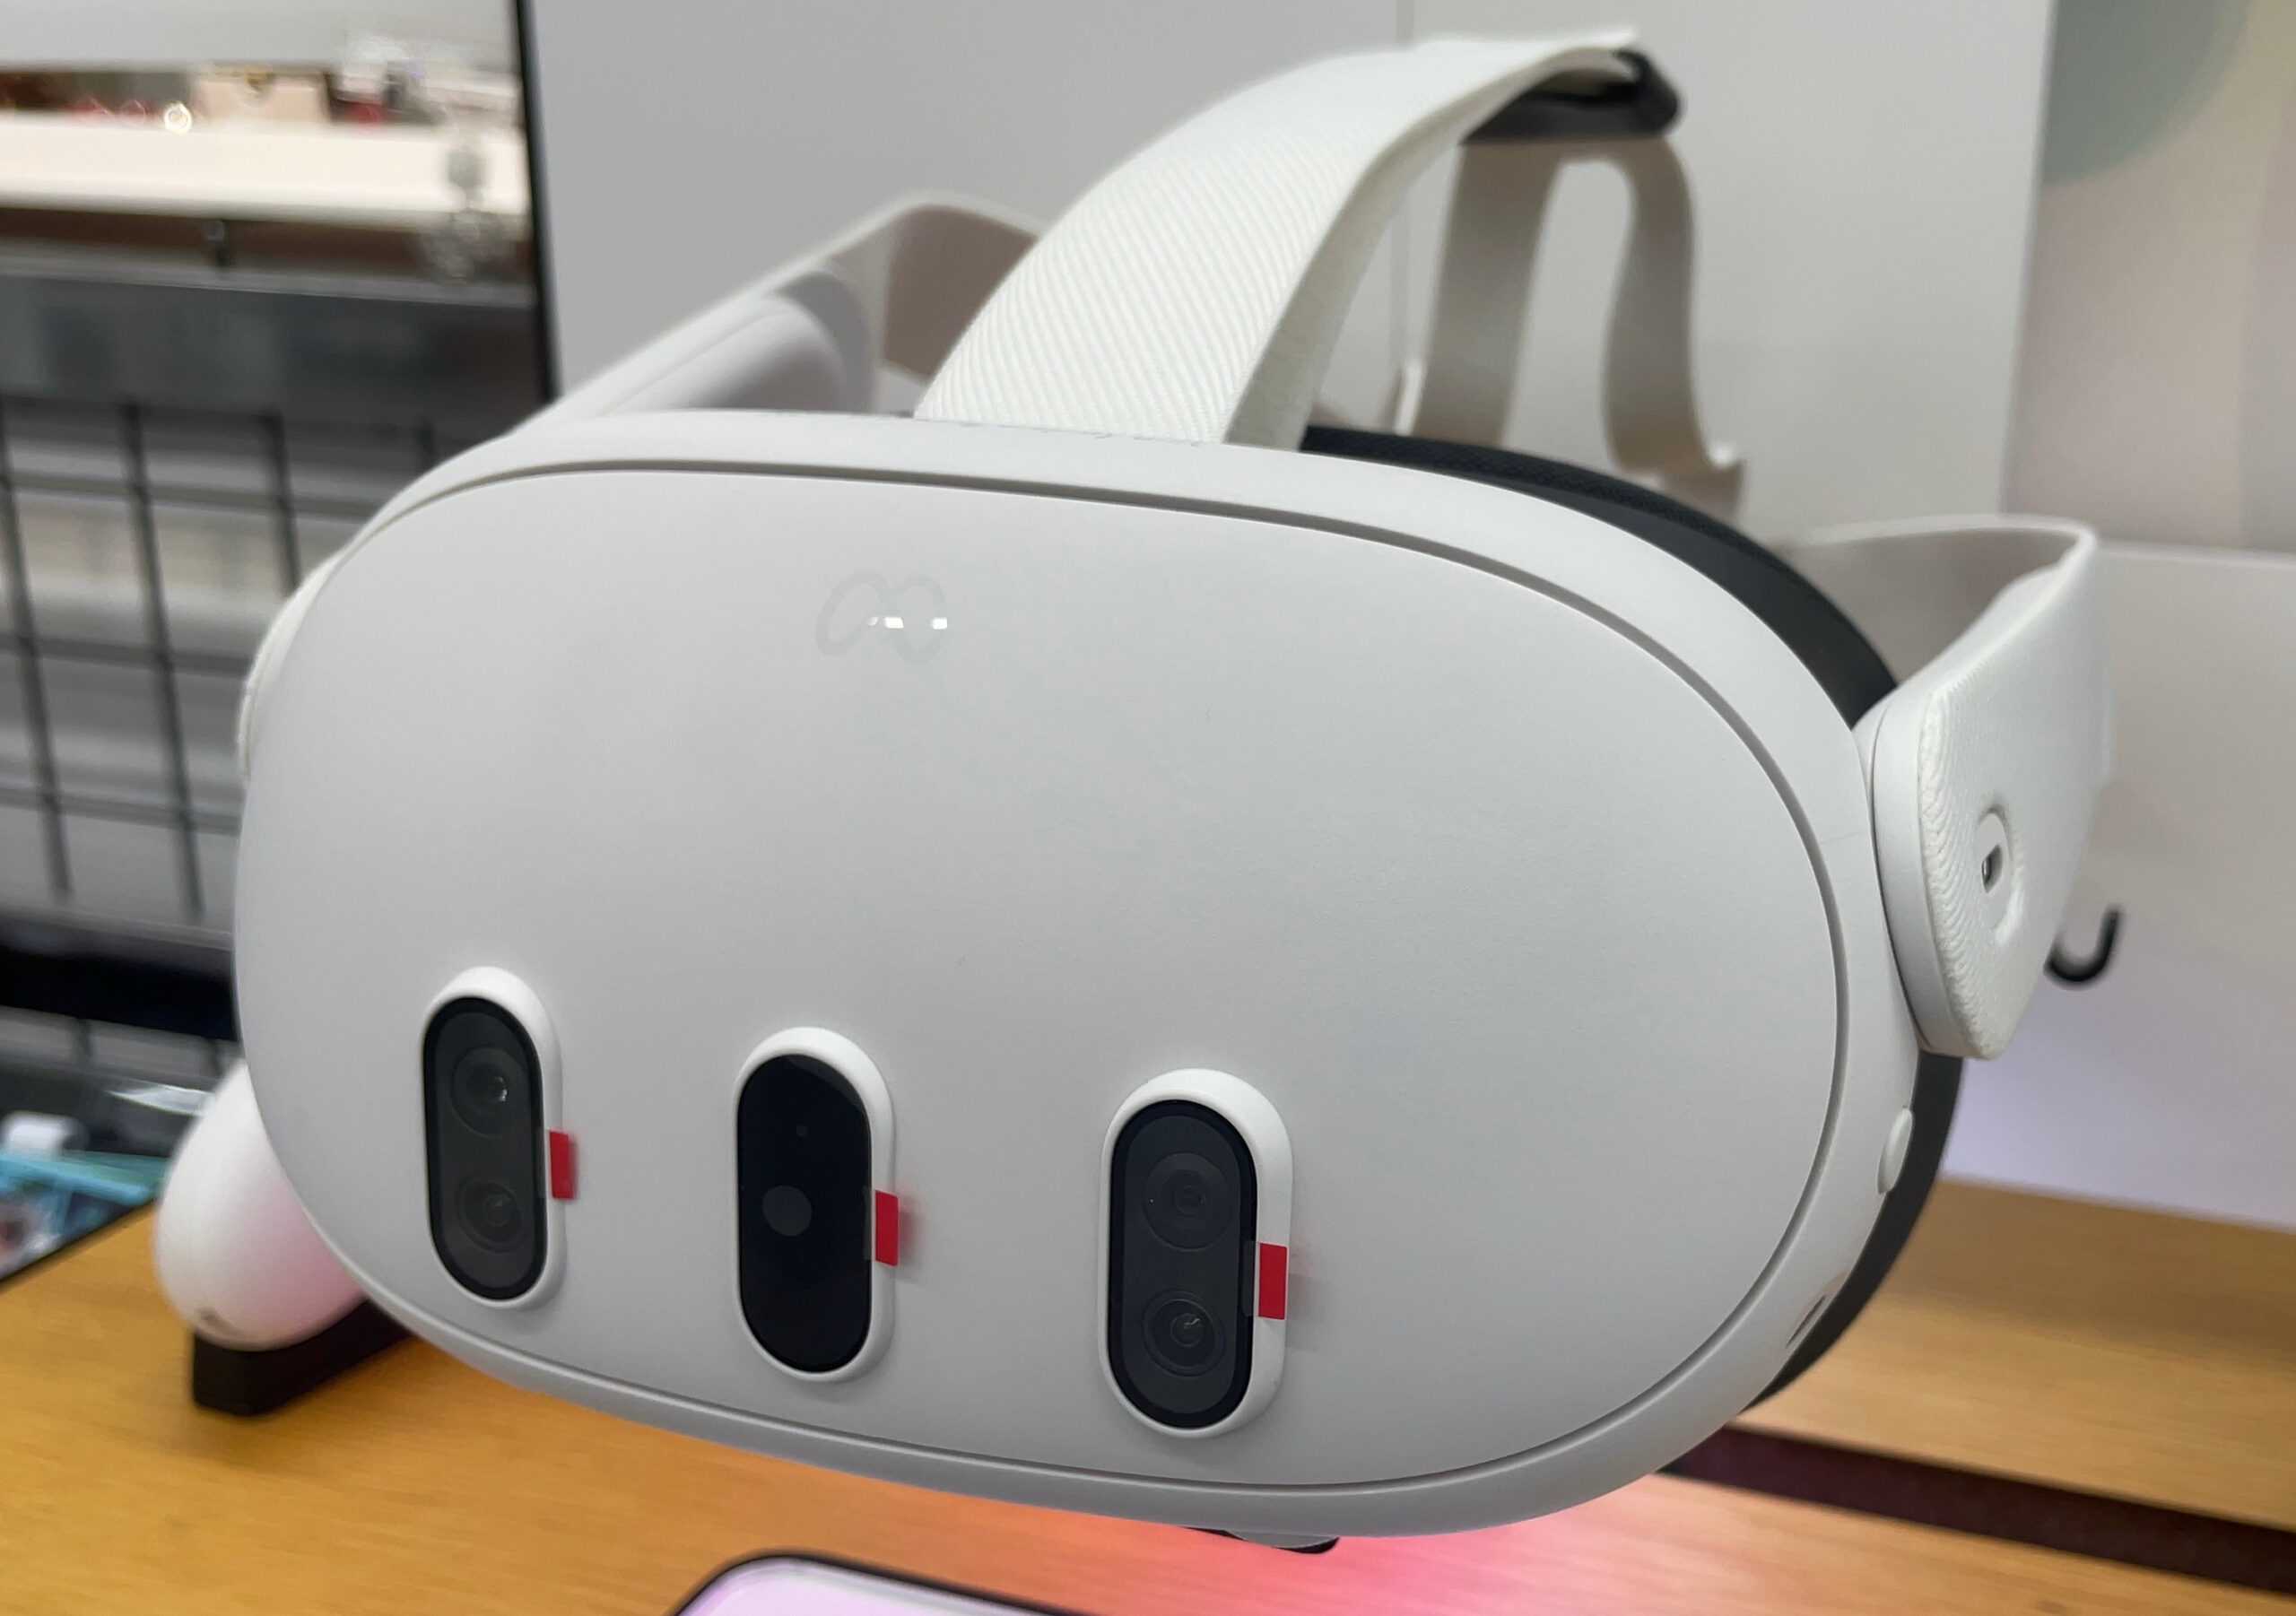
IDC’s second-quarter 2026 trackers just REDREW the XR map. Global shipments of headsets and glasses rose 35.3% year on year — and GLASSES of one kind or another took NEARLY 85% of those units. Headsets held the remaining 15.4%, DOWN from 27.1% a year earlier.
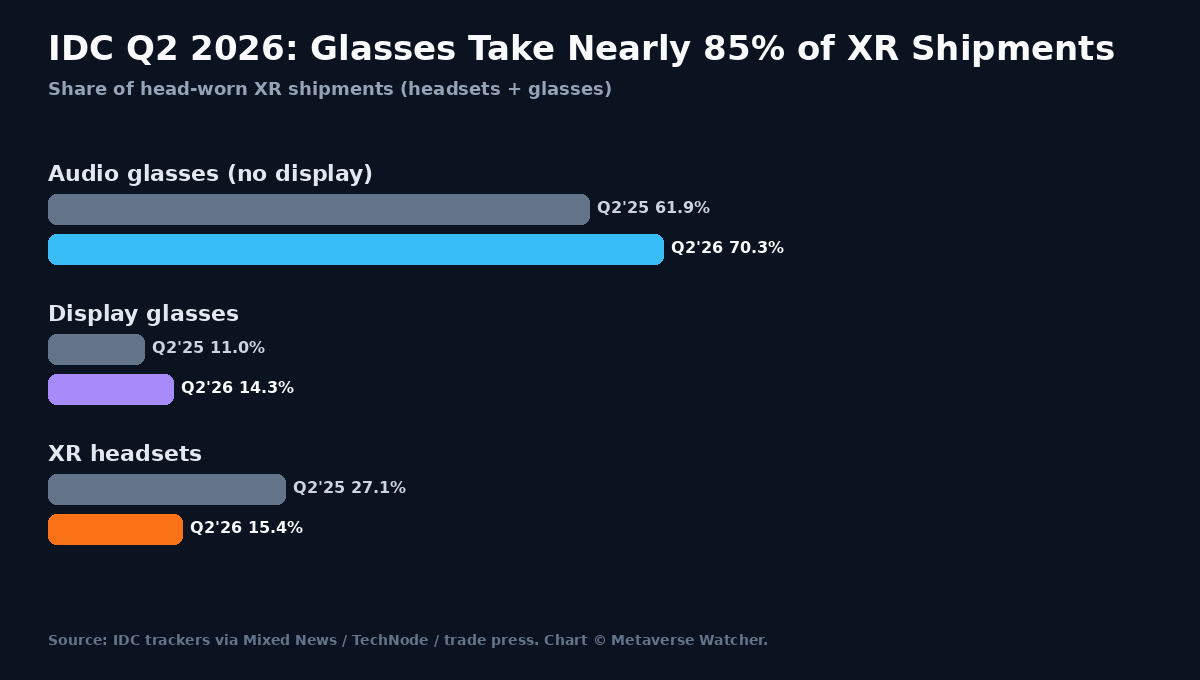
Mixed published the share rundown on September 20. TechNode’s September 17 read of the same IDC trackers adds UNIT COUNTS: about 3.547 million smart-eyewear shipments in the quarter, with audio and camera glasses at 2.494 million, AR/ER glasses at 505,000, and VR/MR headsets FALLING 23.3% to 548,000.
Display-Free Frames Still Carry the Market
The category that SELLS is the one that shows you NOTHING. IDC puts audio glasses — the display-free style that includes Ray-Ban Meta — at 70.3% of shipments, UP from 61.9% a year ago. Display glasses took 14.3%, up from 11%. Together those two lanes moved from 72.9% to 84.6% in twelve months. Headset SHARE fell by the SAME AMOUNT.
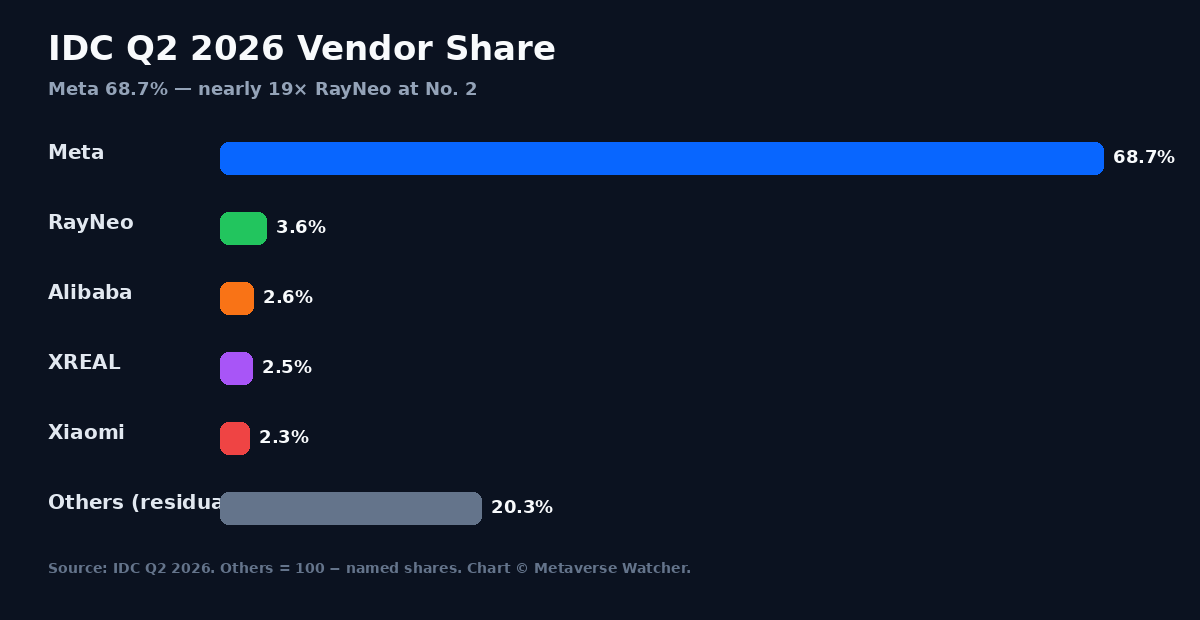
That mix explains the vendor table. IDC puts Meta at 68.7% of head-worn shipments — roughly NINETEEN TIMES RayNeo at 3.6%. Alibaba sits third at 2.6% on Qwen’s traction in China. XREAL and Xiaomi round out the named pack; Xiaomi’s share nearly HALVED year on year as home-market competition intensified.
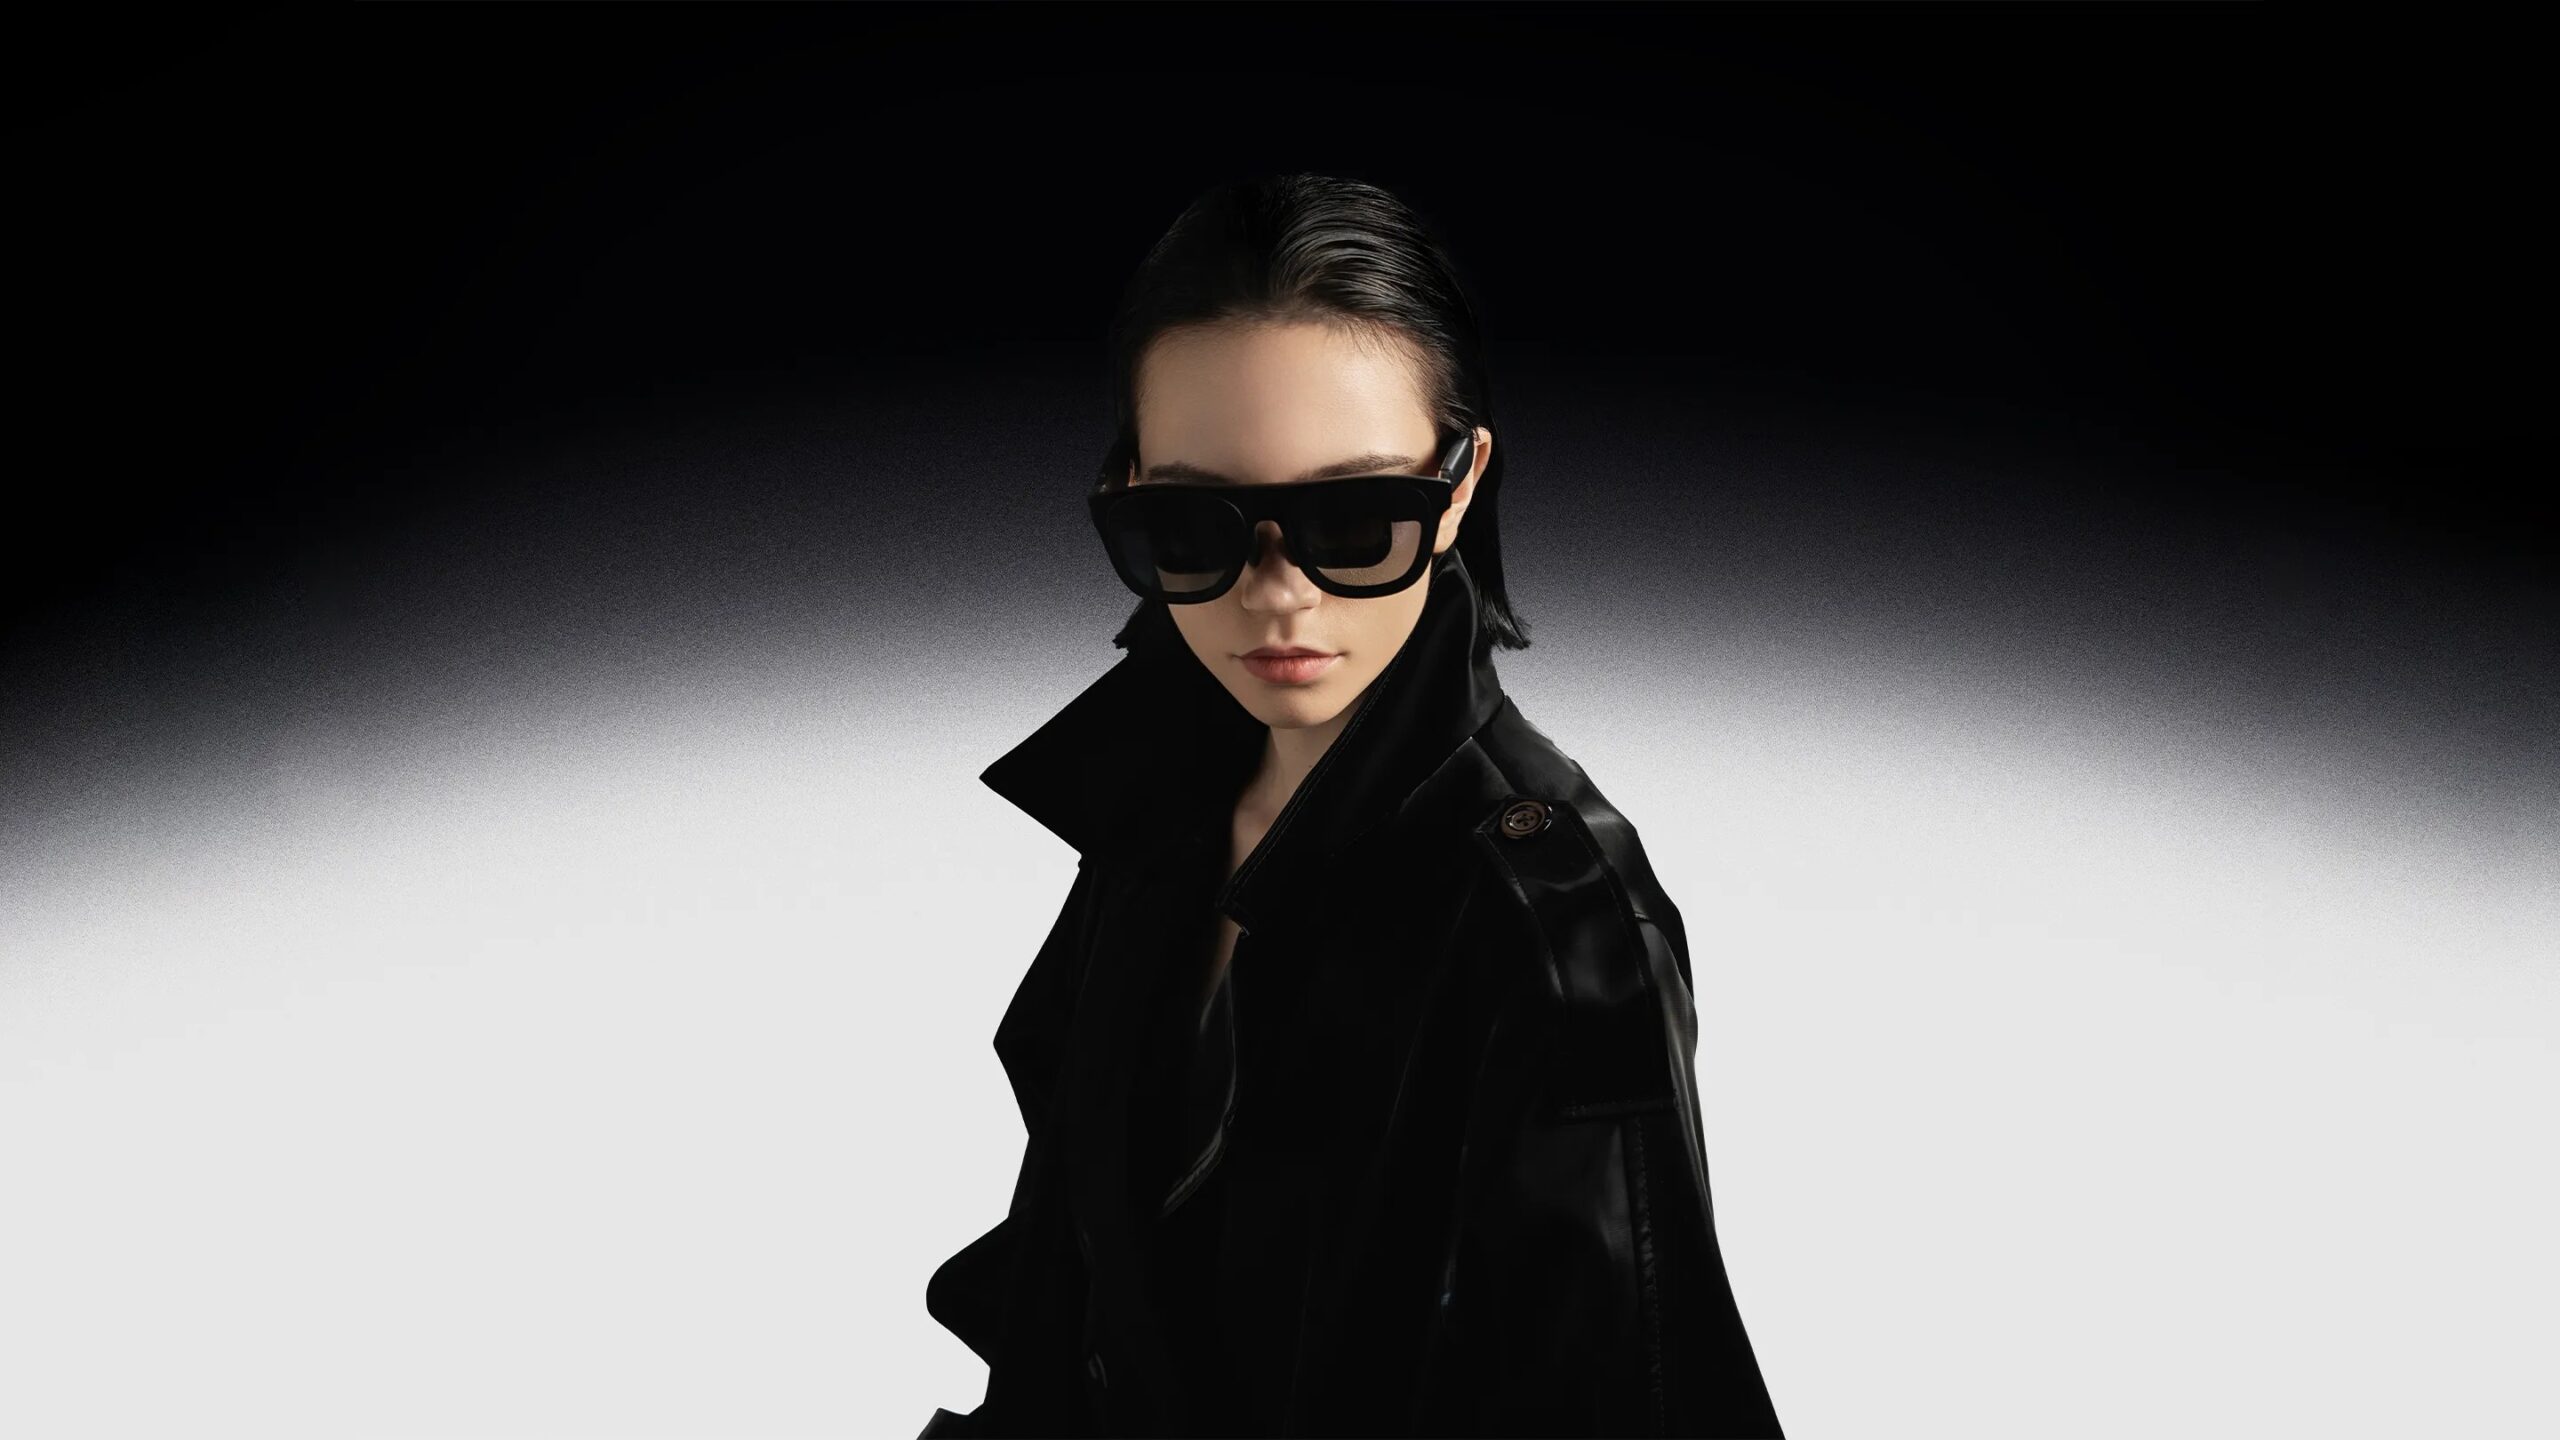
IDC credits Meta’s quarter to PRESCRIPTION lines (Blayzer and Scriber Optics) and cheaper frames that skip EssilorLuxottica fashion branding. RayNeo’s 83.3% year-on-year climb rides low-cost personal-theatre glasses. Growth of 35.3% is a SHARP COOL from the prior quarter’s 130.2%, which IDC blames on tougher comps and a pause between product cycles — not on fading interest.
Display Glasses and Headsets Are Not the Same Bet
If you are building an app or a fleet for the installed base, you are mostly designing for VOICE, camera, and an ASSISTANT. A design that assumes a SCREEN in front of the eye is aiming at 14.3% of shipments — plus the 15.4% headset remnant. Display glasses and headsets together are only 29.7% of the pile.
China’s 120% Figure Is a Different Meter
China’s Ministry of Commerce said September 20 that smart-glasses sales VALUE on key platforms rose 1.2 times (120%) from January through August. That is MONEY on Chinese e-commerce, not global UNIT SHARE. We covered that briefing earlier today. A market can take more yuan for glasses while shipping a different mix — and MOFCOM’s eight-month value series says nothing about the three-month unit stack IDC is comparing.
What the Numbers Do Not Settle
IDC forecasts 26.3% unit growth for 2026, then 40.5% in 2027 and 26.4% in 2028, assuming display-free frames keep leading while display glasses and headsets ramp beside them. Shipments are CHANNEL INFLOW, not a headcount of people wearing anything. The next measurable test for a SECOND PLATFORM is whether Snap Specs, Samsung’s Gemini audio glasses, and XREAL’s Android XR Aura move the share table once they SHIP.
Direction of travel is the CLEAR part. The headset half of the market is LOSING GROUND. Growth has moved to hardware that looks like a pair of glasses.
Sources: MIXED — Glasses take nearly 85% of XR shipments (Sep 20, 2026); TechNode — Global smart eyewear shipments Q2 2026; The Clarity — Meta 68.7% share rundown; IDC blog — Smart Glasses Surge (Q1 context / forecasts); prior MW coverage of China’s MOFCOM 120% sales-value briefing.
1 thought on “IDC: Glasses Take Nearly 85% of XR Shipments in Q2 2026”